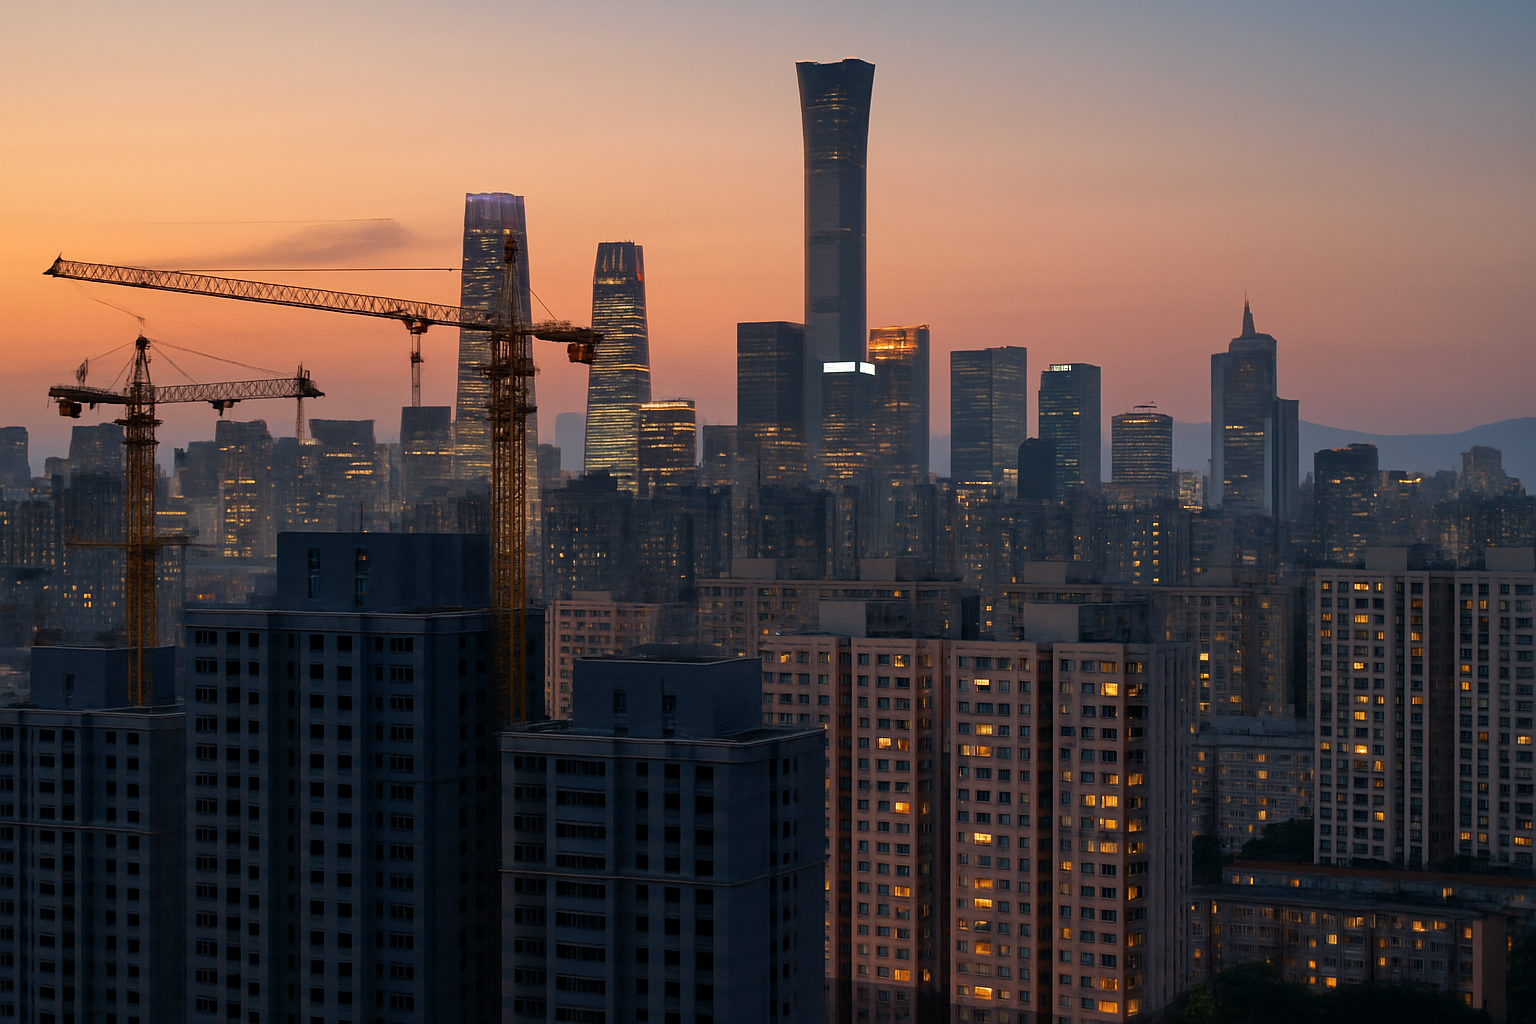
Beijing signals tougher intervention to steady property sector
China’s top leadership on September 26, 2026 instructed government agencies to intensify measures to stabilise the real estate market and increase countercyclical fiscal support, a move that immediately reshaped investor expectations across equity and bond markets. The Politburo called for steps to limit new housing supply in overheated locations, speed up financial support for approved projects, and ease conditions that have constrained home purchases in recent years.
Markets price in renewed policy easing
Asset prices responded quickly to the meeting’s readout. Mainland property shares and broader Chinese stock indices rose during Asian trading on the same day, while onshore bond yields fell, reflecting investor anticipation of more accommodative monetary and fiscal settings. Analysts said the guidance reduced uncertainty over policy direction and increased the likelihood of targeted support measures aimed at accelerating project completions and reducing financing stress for developers.
What the directives mean in practice
The Politburo instructed authorities to increase lending to projects placed on designated assistance lists, relax some home‑purchase restrictions in selected cities, and intensify local fiscal issuance for infrastructure and housing support. The guidance emphasised the twin goals of stabilising prices and ensuring construction and delivery of existing developments. Officials signalled a preference for targeted, city specific steps rather than blanket stimulus, seeking to curb speculative demand while restoring confidence among ordinary buyers and stalled projects.
Why Beijing is acting now
Policymakers face a delicate balancing act. The property sector remains a large component of China’s economy through its links to construction, local government finance and household wealth. After several years of depressed sales and project delays, authorities have grown more worried that prolonged weakness could sap consumption and slow the broader recovery. The Politburo’s intervention on September 26 represents an attempt to close that risk channel by accelerating liquidity and loan support for feasible projects and by nudging local governments to use fiscal tools to stabilise activity.
Risks and limits to the approach
Economists and market participants cautioned that signalling alone will not solve deep structural issues such as developers’ heavy leverage and long term demand shifts. Targeted support can help deliver stalled projects and limit financial spillovers, but it risks favouring larger state linked firms and could perpetuate moral hazard if not tightly conditional. Observers also noted that global financial conditions, including rising overseas bond yields and tighter credit in major economies, constrain how far China can loosen policy without creating currency or capital flow pressures.
What to watch next
Investors will look for concrete follow up in coming days, including directives from the People’s Bank of China on lending facility parameters, guidance from the Ministry of Finance on local government special bond issuance, and the release of white lists identifying projects eligible for priority funding. Monthly and quarterly property and construction data will be scrutinised for signs that sales and deliveries are responding to policy incentives. How Beijing calibrates support will be crucial for market sentiment and for the health of related sectors of the economy.
The September 26, 2026 Politburo readout marks a renewed phase of active policy management focused on preventing a deeper drag from the property sector on China’s growth prospects. The near term market reaction shows investors view the pronouncements as materially supportive, but the effectiveness of measures will depend on speed of implementation and the scale of concrete fiscal and credit support that follows.