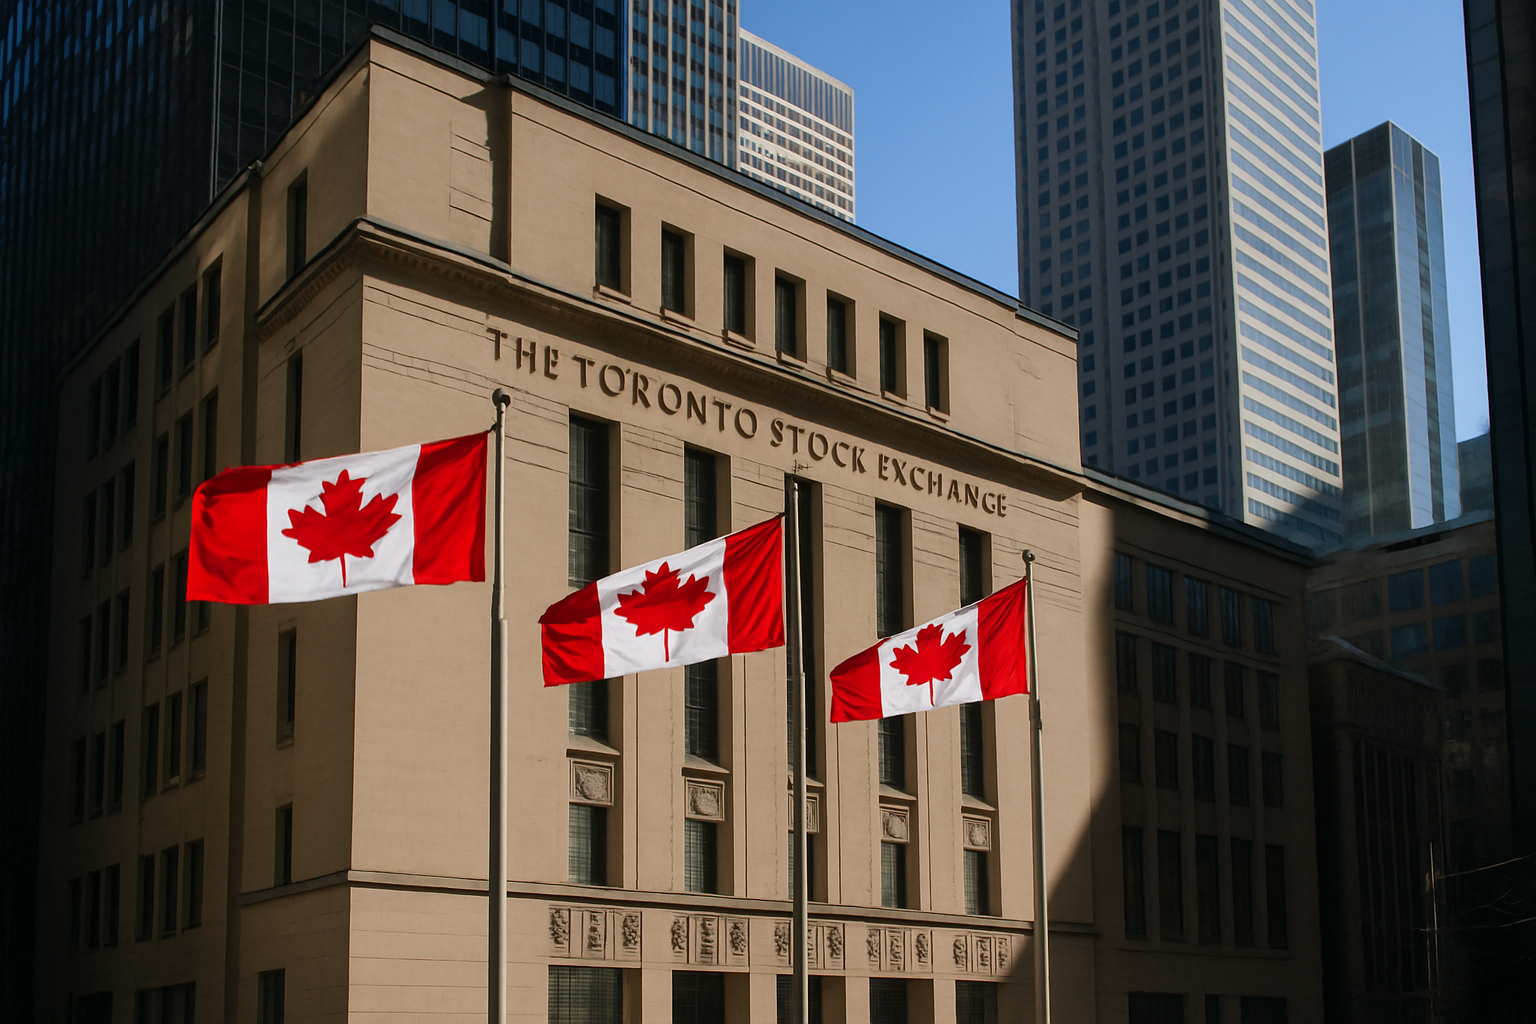
TMX Group Limited on September 26, 2026 priced a C$1.1 billion private placement of senior unsecured debentures, the company said in a regulatory notice published the same day. The multi-tranche deal, sold to accredited Canadian investors, included shorter and longer dated series and was described by TMX as an opportunistic funding exercise to diversify its debt profile and strengthen liquidity as the exchange operator navigates an active schedule of capital needs.
Deal structure and near term impact
The offering comprised multiple series of senior unsecured debentures across staggered maturities, with the largest tranches scheduled between 2028 and 2033. TMX said proceeds will be used for general corporate purposes, including refinancing short-term debt and supporting ongoing investments in technology and market infrastructure. Pricing on the nearer-term series was set at yields modestly above Canada sovereign curve levels, reflecting investor appetite for high quality Canadian issuers even as global rates remain elevated.
For TMX, which operates the Toronto Stock Exchange and a suite of clearing and market data businesses, the transaction gives management incremental flexibility to fund strategic projects and to manage its maturity profile after several years of capital spending and corporate activity. Market participants noted that Canadian issuers have continued to access the debt markets this month, and TMX’s placement is consistent with broader corporate funding patterns in Canada where companies have sought to lock in financing before potential swings in rate expectations.
Why this matters for Canada’s companies and markets
TMX Group is one of Canada’s central market infrastructure companies, so its financial moves carry signal value. By successfully placing a sizable amount of senior unsecured debt with domestic institutional buyers, TMX has reinforced the depth of investor demand for investment grade Canadian credits. That in turn lowers borrowing frictions for other Canadian corporates that rely on a liquid domestic market for funding. A well functioning capital market benefits pension funds, insurers and asset managers that are sizeable purchasers of long dated paper.
The timing also matters. Canadian issuers have faced a backdrop of higher-for-longer interest rates and tighter global liquidity since central banks around the world pivoted in 2022 and 2023. When a systemically important issuer like TMX taps the market and secures attractive terms, it is read by some strategists as a sign that domestic fixed income investors remain confident in Canadian credit fundamentals and the prospects for yield relative to alternative markets.
Balance sheet and strategic context
TMX has been investing in its technology stack, market data capabilities and clearing services as it positions for growth in areas such as fixed income trading, pensions-focused products and data services. Management has also laid out priorities to maintain a conservative balance sheet, while pursuing selective acquisitions or partnerships to expand non-transaction revenue. The fresh debt capacity leaves the company in a position to continue that strategy without immediately tapping equity markets or drawing down short-term lines.
Analysts who track TMX say the company’s revenue is increasingly diversified away from equity listing fees alone, toward recurring data and post-trade services. That structural shift makes the firm more resilient to episodic swings in public listing activity, and it supports a credit profile that can sustain well-structured debt offerings.
Investor reception and market signals
Initial market commentary indicated the placement was well received by Canadian institutional accounts. Observers pointed to the participation by pension funds and insurance buyers seeking duration and stable yield in a market where high-quality paper with multi-year duration is still in demand. At a macro level, continued flows into corporate debt from domestic long-term investors supports a stable environment for Canadian corporate funding even as global risk sentiment shifts.
Finally, the deal underscores the role of domestic capital pools in financing Canadian corporate and infrastructure ambitions. For issuers, the availability of deep, patient Canadian capital can reduce reliance on foreign funding and hedge some currency and cross-border execution risk.
What to watch next
Market watchers will look for TMX’s next regular financial disclosures for more detail on how management intends to allocate proceeds and whether the company will accelerate any planned capital projects. Credit analysts will monitor covenant language, if any, tied to the new instruments and how the new issuance changes TMX’s maturity ladder. For the broader market, additional large Canadian issuers coming to market in the weeks ahead will show whether investor demand seen for TMX can be sustained.
Because TMX sits at the center of Canada’s capital markets, the success of this transaction is likely to be read as a modest positive signal for Canada’s corporate funding outlook in the near term.